Dawn Griffin February 1, 2018
Your house is feeling a little too small. It’s actually feeling A LOT too small. When you bought it, there was just you or just the two of you. But now? Well now, there’s you plus three small humans, a canine, two guinea pigs, and a fish.
While you have a great job and good credit, you are low on cash because you spent the last 8 years paying off student debt. You don’t have a down payment for the new house. However, there’s a lot of equity in your current home. You bought during the recession at a great price and neighborhood values have been steadily improving.
How do you access your equity without first selling your current home? Moving twice is not an option, because (as aforementioned) three small humans, one canine, two guinea pigs, a fish and a pretty demanding work life will not allow a routine break of that magnitude.
A bridge loan is secured by the equity in your existing home. A bridge loan allows you to access up to 85% of the total value of the home you are selling. For example, let’s say your current home is worth $300,000 and you owe $150,000. The bridge loan would allow you to pull out the remaining $105,000 in equity for the down payment on your new home.
[($300,000 x .85) – $150,000 = $105,000]
Yay! This allows you to write a competitive offer, not contingent on the sale of your current home. You only move one time and you have purchased the new home with a permanent mortgage. This means you do not have to refinance down the road and incur additional closing costs or risk an interest rate jump.
On top of that, you selected the right Realtor to help with the sale of your existing home so it will sell in a hot minute and you won’t have to worry about carrying double payments for an extended time.
Stay up to date on the latest real estate trends.
September 2026 housing numbers and what home buyers and sellers need to know.
Many local butcher shops are longtime neighborhood institutions that still offer something increasingly difficult to find at a supermarket: personal service, specialty… Read more
Recognition
The Dawn Griffin Group is named St. Louis Magazine's Best Real Estate Agent for the third year in a row.
Halfway into the first full season, here are some things I've learned about pool ownership.
Save Big By Finding Dates, Eligible Items and Shopping Limits
New shops and restaurants in downtown Kirkwood and beyond
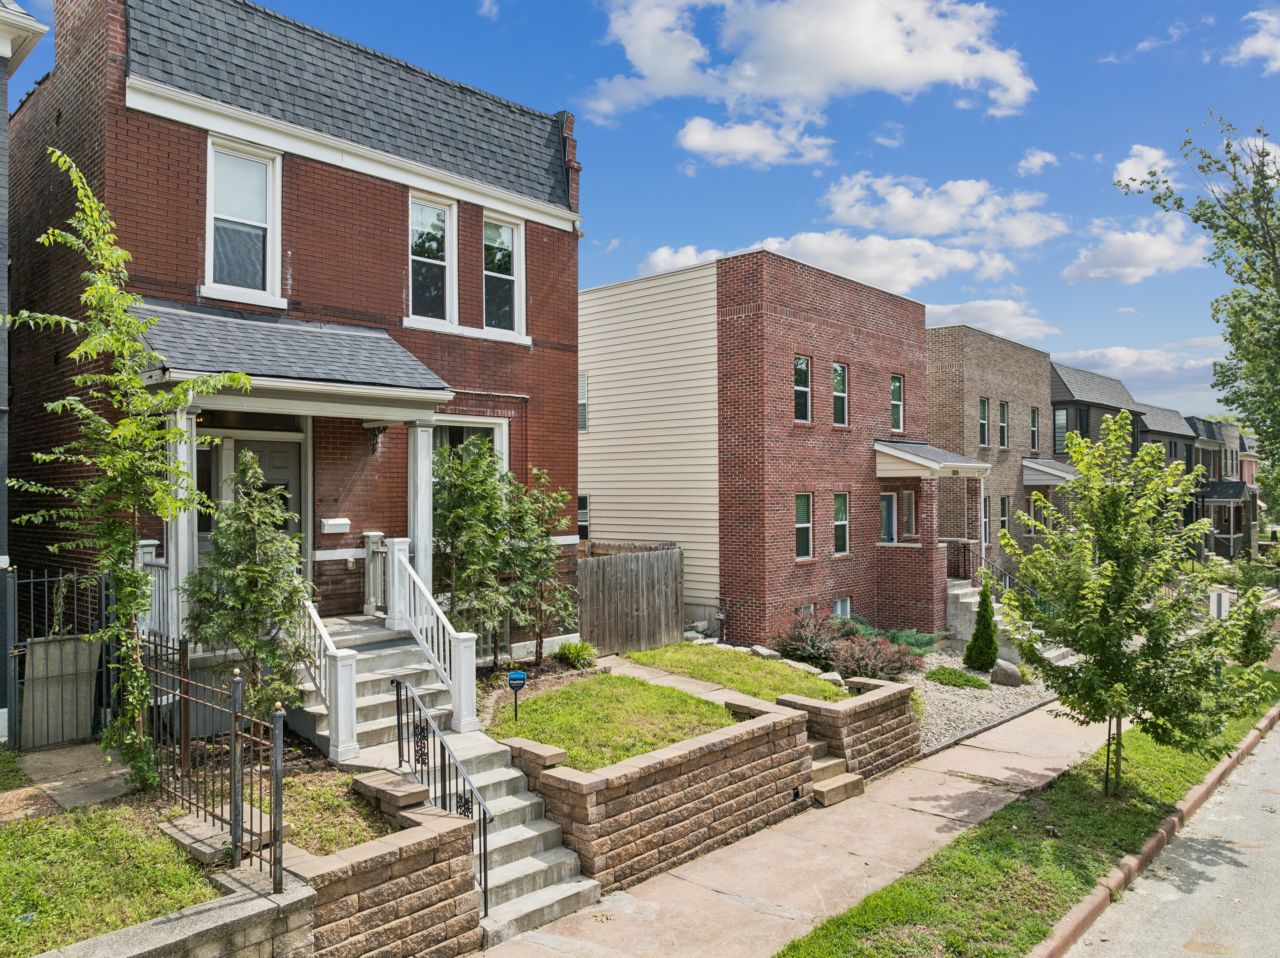
3329 Vista Avenue sits in a neighborhood that has been rewritten, quite literally, more times than almost any other pocket of the city.
We regularly use these same resources to help our clients before, during, and long after closing.
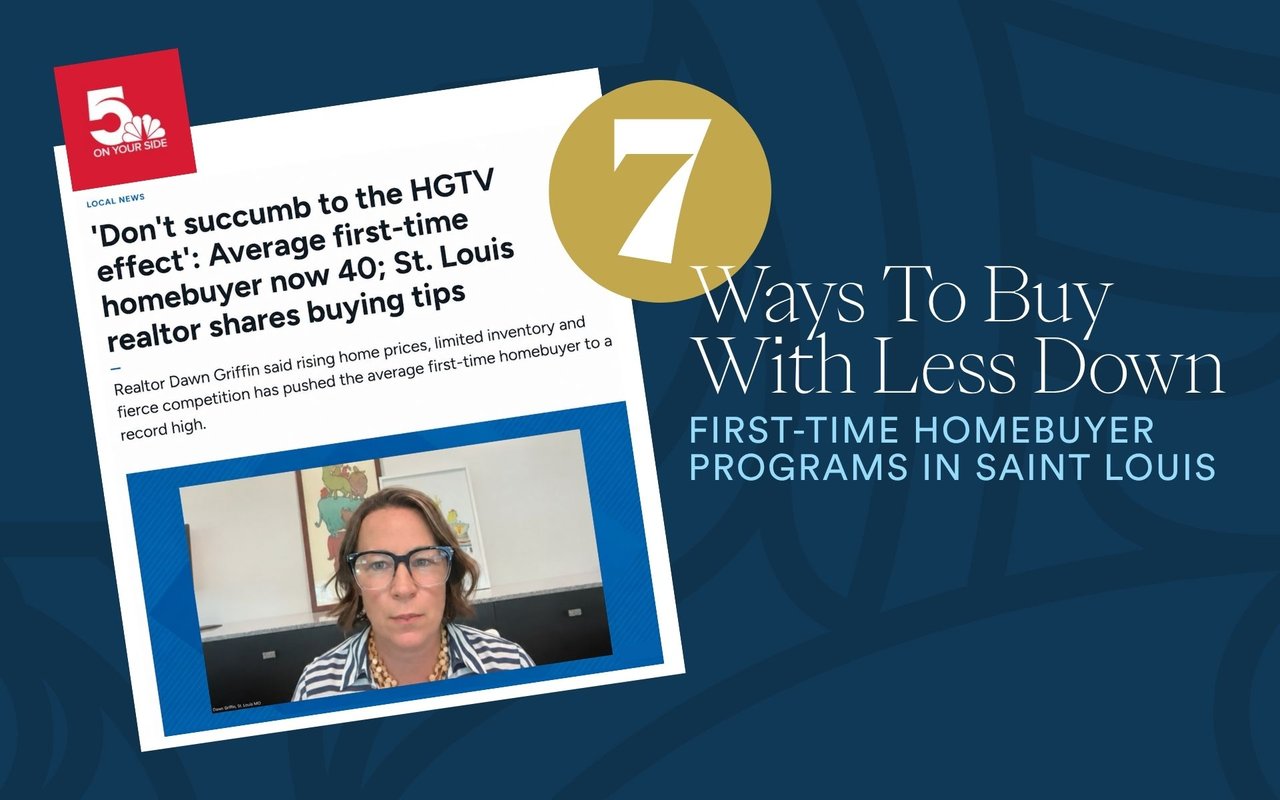
Here are seven of the most popular St. Louis first-time homebuyer programs available.
Partner with a team that values honest advice, strategic guidance, and exceptional service. With decades of experience and over 1,000 successful transactions, we're committed to helping you achieve your real estate goals with confidence.
Planning a move? Thinking about selling? Want to talk real estate?
Dawn Griffin Group
3636 S Geyer Rd Ste #100 St. Louis, MO 63127