
Dawn Griffin May 18, 2023
When seeking a home loan, one of the most crucial decisions is choosing between fixed-rate and adjustable-rate mortgages. Each option has its own set of advantages and considerations. This article will compare adjustable rate mortgages and fixed rate mortgages, helping you make an informed decision based on your financial goals and circumstances.
Fixed Rate Mortgage: With a fixed rate mortgage, the interest rate remains unchanged throughout the loan term. This provides stability and allows for predictable monthly payments, regardless of market fluctuations.
Adjustable Rate Mortgage: ARMs typically have an initial fixed-rate period, often lasting three, five, seven, or ten years. After this period, the interest rate adjusts periodically, typically annually. This means that the rate and subsequent monthly payments can fluctuate over time.
Fixed Rate Mortgage: Fixed rate mortgages usually have slightly higher initial interest rates compared to ARMs. However, they provide the benefit of rate certainty, shielding borrowers from potential rate increases in the future.
Adjustable Rate Mortgage: ARMs often start with lower interest rates during the initial fixed-rate period. This can make them attractive for those planning to sell or refinance before the adjustment period begins.
Fixed Rate Mortgage: With a fixed rate mortgage, the interest rate and monthly payments remain constant throughout the loan term. This stability is beneficial if you prefer to budget with certainty or expect interest rates to rise over time.
Adjustable Rate Mortgage: Once the initial fixed-rate period ends, ARMs adjust according to market conditions. The adjustment is based on a predetermined index, such as the U.S. Treasury or LIBOR rates, plus a margin. This means that your monthly payments may increase or decrease based on the market.
Fixed Rate Mortgage: Fixed rate mortgages provide stability and protection against rising interest rates. They are suitable for those who prefer long-term financial certainty and plan to stay in their homes for an extended period.
Adjustable Rate Mortgage: ARMs can offer lower initial payments and are ideal for borrowers who anticipate changes in their financial situation or plan to sell or refinance before the rate adjustment period. However, they carry the risk of higher future payments if interest rates rise significantly.
Fixed Rate Mortgage: Most fixed rate mortgages have terms of 15, 20, or 30 years, allowing borrowers to spread out their payments over an extended period.
Adjustable Rate Mortgage: ARMs often have shorter initial fixed-rate terms, such as 3, 5, 7, or 10 years. However, they can be refinanced or paid off early without penalty, providing flexibility for those who plan to move or refinance before the adjustment period.
The choice between a fixed rate mortgage and an adjustable rate mortgage depends on your financial goals, risk tolerance, and future plans. Fixed rate mortgages offer stability and protection against rising rates, while ARMs provide flexibility and potentially lower initial payments. Consider your long-term housing plans, current financial situation, and market conditions when making a decision. Consulting with a mortgage professional can also help you navigate the options and choose the best mortgage for your specific needs. Reach out to us for a list of mortgage companies that our clients have had success working with.
Stay up to date on the latest real estate trends.
Tips, Tools, & Resources
Who to call before the guests arrive, the snow falls, or you head out of St. Louis for the holidays.
Around St. Louis
Comprehensive 2026 guide to shopping small in St. Louis — books, food, vintage, kids, and so much more.
Around St. Louis
Handmade gifts, vintage finds, and neighborhood traditions: 25 markets to plan your holiday weekends around.
Selling A Home
National media exposure, international reach, and a marketing plan built around your St. Louis home.
Real Estate Market News
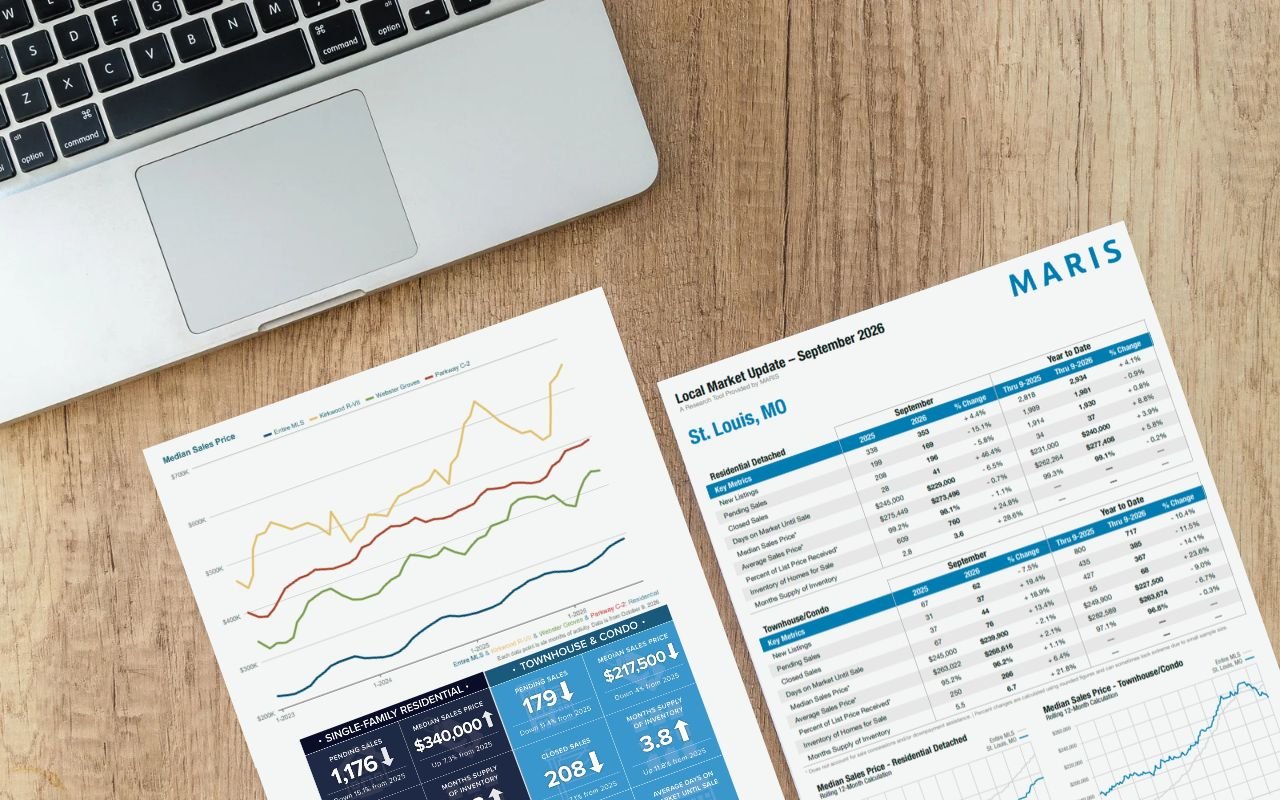
October 2026 Insights into the local housing market
Around St. Louis
Let a local favorite handle the turkey, the sides or just the pie this year, with every deadline you need in one place.
Buying A Home
How UAD 3.6 affects appraisal costs, timing, and your home purchase
Selling A Home
You make the introduction. We’ll take it from there.
Selling A Home
The questions to ask, and the numbers to check, before you sign a listing agreement
Partner with a team that values honest advice, strategic guidance, and exceptional service. With decades of experience and over 1,000 successful transactions, we're committed to helping you achieve your real estate goals with confidence.
Planning a move? Thinking about selling? Want to talk real estate?

Dawn Griffin Group
3636 S Geyer Rd Ste #100 St. Louis, MO 63127