Dawn Griffin August 25, 2021
Tapping your home equity can be a convenient, low-cost way to borrow large sums at favorable interest rates to pay for home repairs or debt consolidation. However, the right type of loan depends on your needs and what you plan to use the money for.
The most common ways to access the equity in your home are a HELOC, a home equity loan and a cash-out refinance. A mortgage lender or your financial institution can help you determine which way makes the most sense for you.
There are several ways to use your home equity. Below are four of the most frequent:
Home improvement projects are one of the most common ways home equity is used. Upgrades can make your home more comfortable and could raise the home’s value. Consider the ROI on your project. For some people, the return on investment isn’t as important if they are planning to stay in the home a while and want a better kitchen for the family to enjoy. But if you are planning to sell within the next five years, you should do your research. Remodeling Magazine’s annual Cost vs. Value Report is a useful tool.
If you have high-interest credit card debts, personal loans or car loans, you might consider using a home equity loan or cash-out refinance to pay them off. This essentially rolls those balances into your new loan, typically with a lower interest rate than other lines of credit.
Some homeowners choose to use their home equity to invest in the stock market or real estate, typically in a vacation home or rental property. You will want to weigh the rate of return you expect to achieve on a long-term investment versus the interest rate of the mortgage or home equity line of credit.
Equity is a great nest egg. At retirement you can consider selling your home and downsizing, using the profits of your equity to boost your income.
Home equity is also sometimes utilized for other expenses like college costs, emergency expenses, business expenses, or even weddings. Again, you will want to weigh the risks with your lender or financial planner.
If you want to learn more about home equity or are you looking to buy or sell a home, reach out. We can help answer questions and provide a list of lenders other clients have used.
Stay up to date on the latest real estate trends.
September 2026 housing numbers and what home buyers and sellers need to know.
Many local butcher shops are longtime neighborhood institutions that still offer something increasingly difficult to find at a supermarket: personal service, specialty… Read more
Recognition
The Dawn Griffin Group is named St. Louis Magazine's Best Real Estate Agent for the third year in a row.
Halfway into the first full season, here are some things I've learned about pool ownership.
Save Big By Finding Dates, Eligible Items and Shopping Limits
New shops and restaurants in downtown Kirkwood and beyond
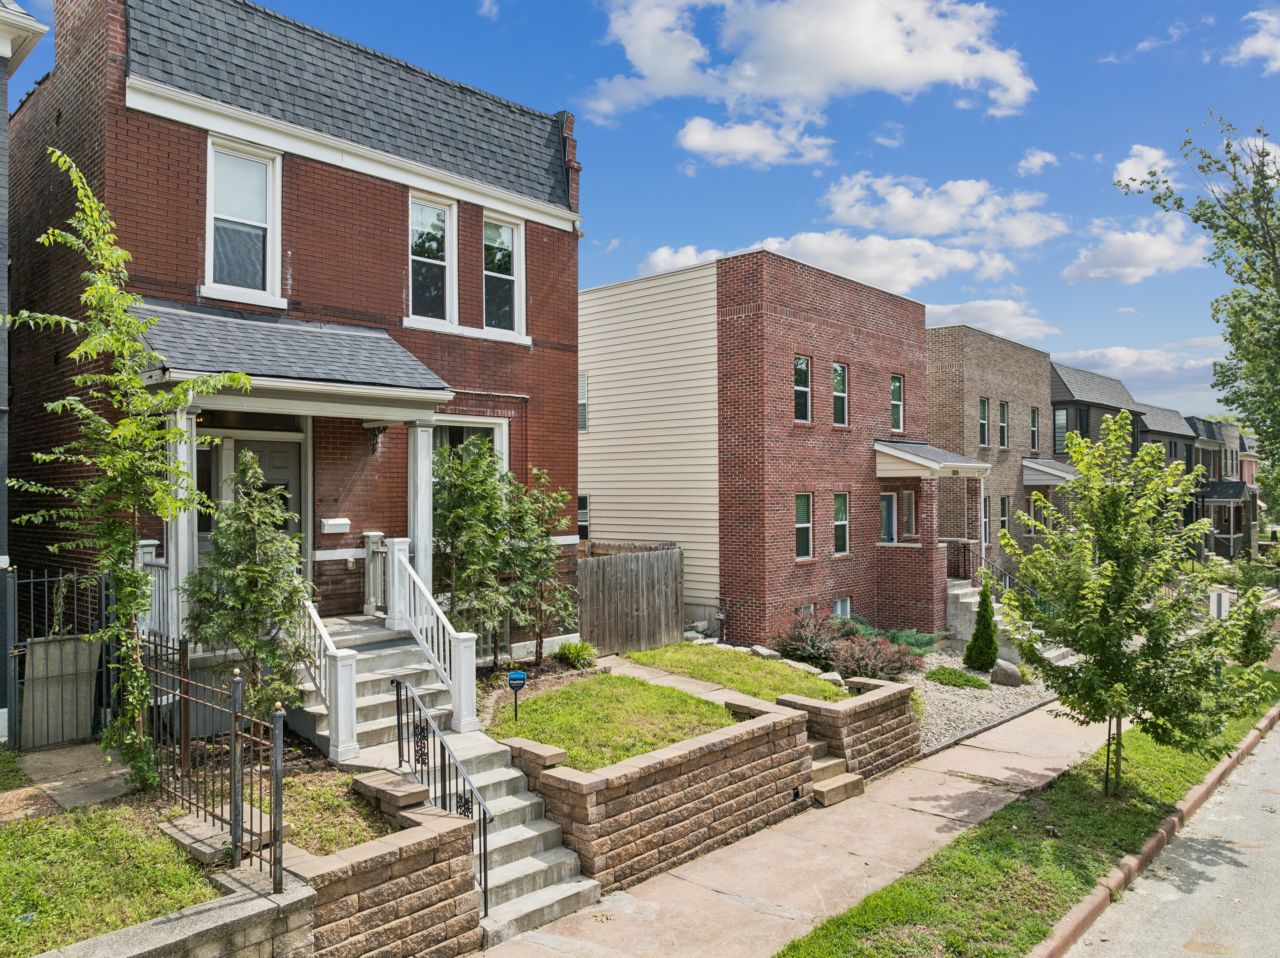
3329 Vista Avenue sits in a neighborhood that has been rewritten, quite literally, more times than almost any other pocket of the city.
We regularly use these same resources to help our clients before, during, and long after closing.
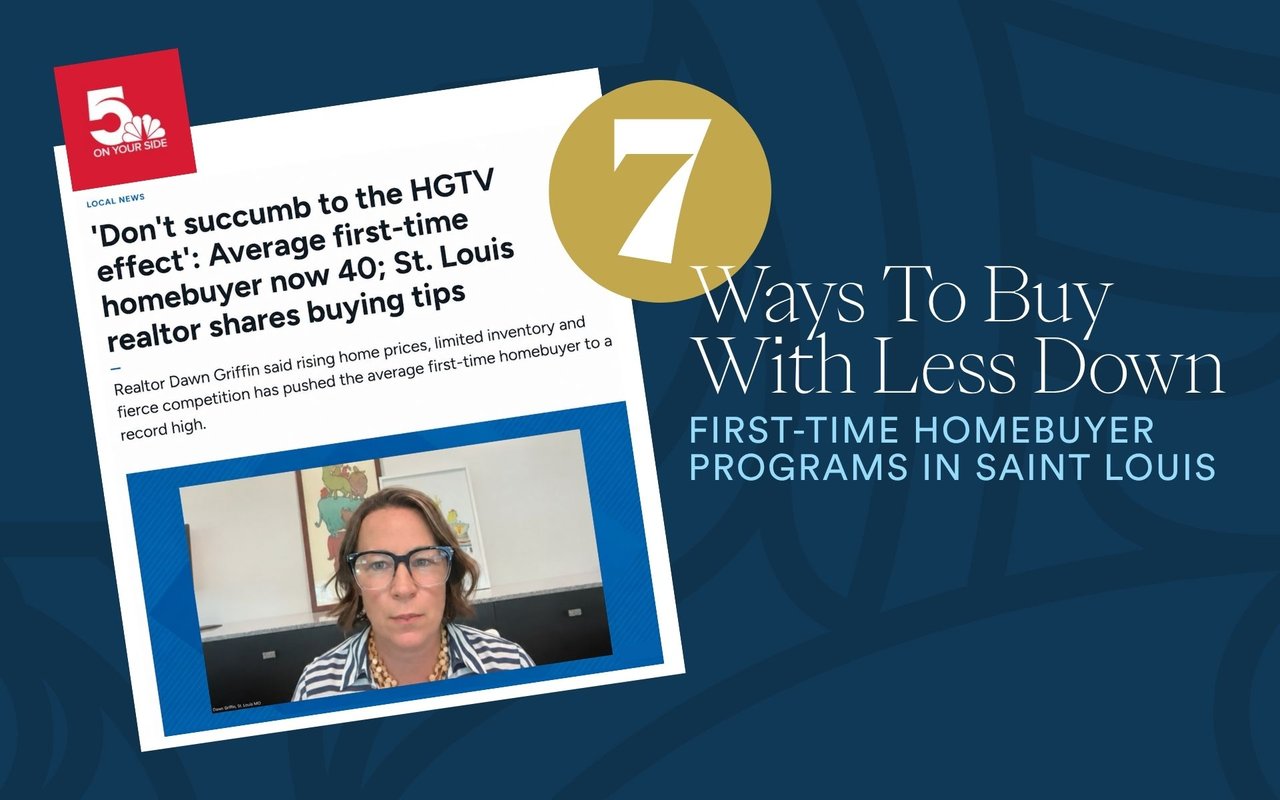
Here are seven of the most popular St. Louis first-time homebuyer programs available.
Partner with a team that values honest advice, strategic guidance, and exceptional service. With decades of experience and over 1,000 successful transactions, we're committed to helping you achieve your real estate goals with confidence.
Planning a move? Thinking about selling? Want to talk real estate?
Dawn Griffin Group
3636 S Geyer Rd Ste #100 St. Louis, MO 63127